
Part of our Medicare and Medicaid Help for Families guide
Leaving Medicare Advantage: How the Medigap Trial Right Works
Picture this: Mom tried a Medicare Advantage plan this year, her favorite specialist turned out to be out of network, and now she wants her old Medigap policy back.
If this was her first time in Medicare Advantage, she may have a federal "trial right." Leave within the first 12 months, and Medigap insurers must sell her certain policies without health questions. She can apply as early as 60 days before the plan ends and no later than 63 days after. Confirm with SHIP before canceling anything.
This guide is for US families helping a parent who tried Medicare Advantage and is having second thoughts. You get a "which door fits?" quiz, a made-up example timeline, myth vs fact cards, and a free one-page check.
Did you know? Medicare Open Enrollment lets you switch from Medicare Advantage back to Original Medicare, but it does not reopen Medigap. Medicare.gov says your Medigap Open Enrollment Period is a one-time period that does not repeat every year like Medicare Open Enrollment. Medicare.gov: Medigap Open Enrollment and guaranteed issue rights
What is the Medigap trial right?
It is a federal guaranteed issue right for people trying Medicare Advantage for the first time. If they switch back to Original Medicare within the first 12 months, a Medigap insurer cannot refuse to sell the policies the right covers, cannot charge more because of health problems, and cannot add a pre-existing condition exclusion.
The rule lives in section 1882(s)(3) of the Social Security Act. Medicare's booklet Understanding Medicare Advantage Plans (April 2026) puts it simply: if you join a Medicare Advantage plan for the first time and you are not happy with it, you have a trial right to buy a Medigap policy and a separate Medicare drug plan if you return to Original Medicare within 12 months.
There are two doors into the trial right. Which one fits changes what Mom can buy.
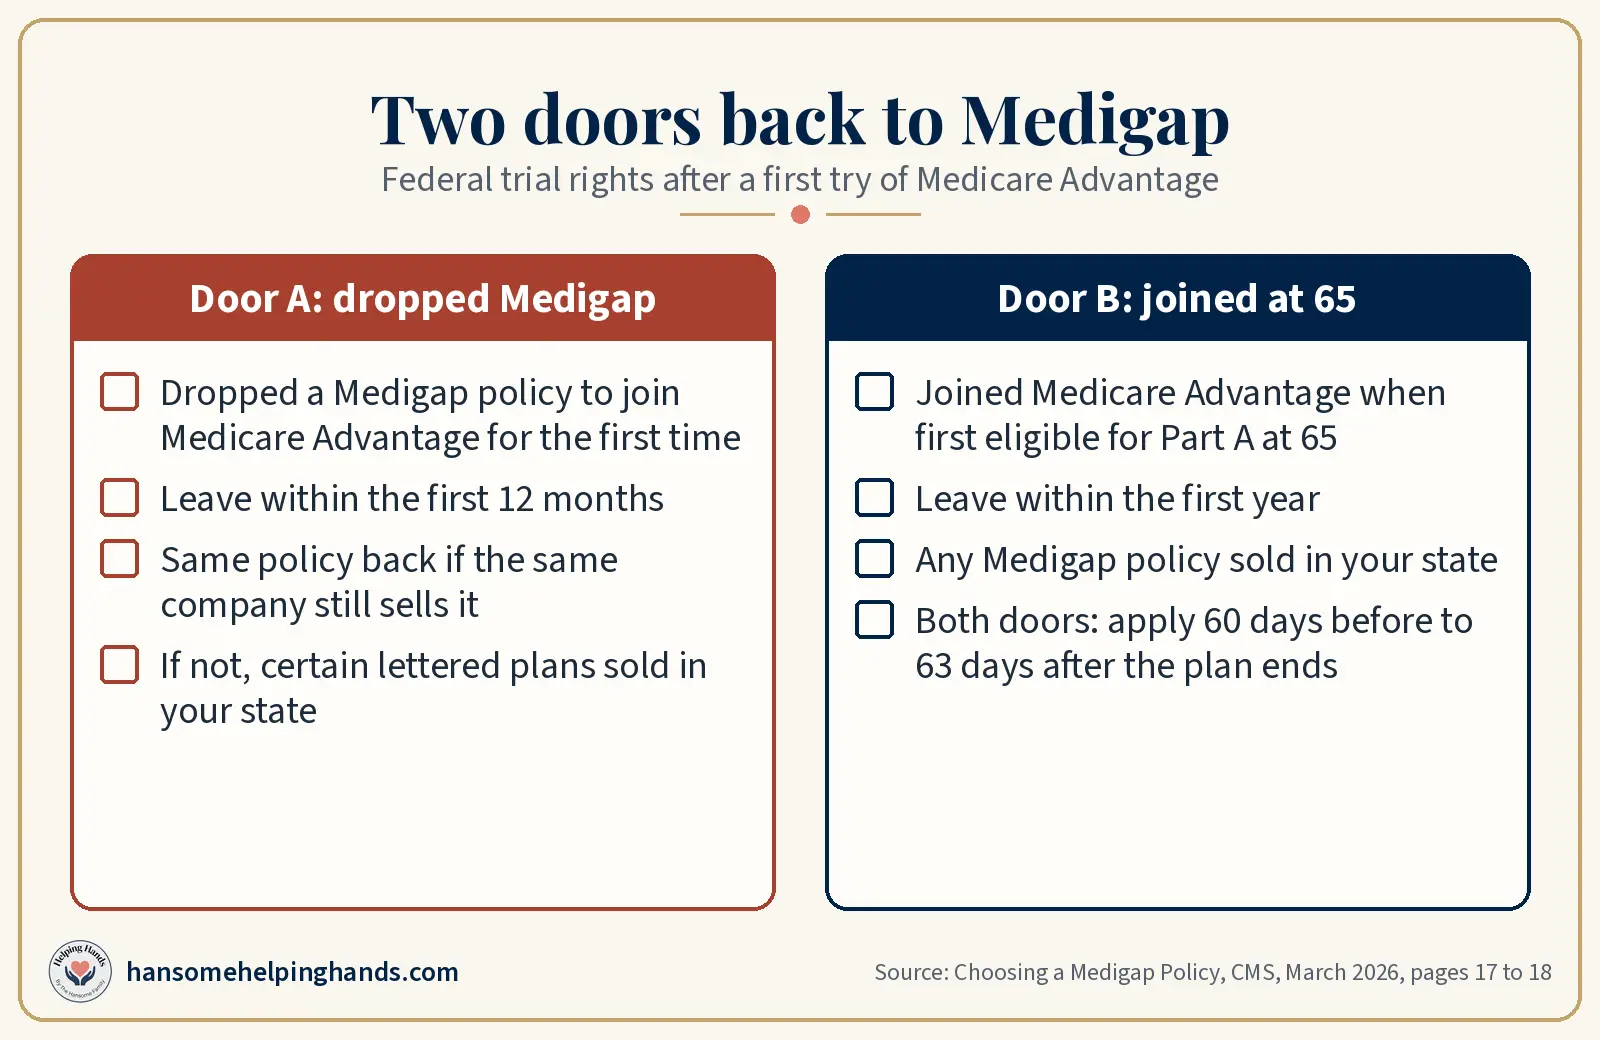
Door A: she dropped Medigap to try Medicare Advantage for the first time
If she dropped a Medigap policy to join a Medicare Advantage plan for the first time, and she has been in the plan less than a year, she can buy back the policy she had, if the same insurance company still sells it. If it is not available, she can buy certain other lettered plans sold in her state.
Which letters? The March 2026 Choosing a Medigap Policy guide lists Plans A, B, D, and G, plus Plans C and F only for people who were eligible for Medicare before January 1, 2020. Medicare.gov's when can I buy a Medigap policy tool also lists Plans K and L. When two official pages differ, ask SHIP which list applies in your state.
Door B: she joined Medicare Advantage when first eligible at 65
If she joined a Medicare Advantage plan when she was first eligible for Medicare Part A at 65, and within the first year she decides to switch to Original Medicare, she can buy any Medigap policy sold by an insurance company in her state. This door does not require that she ever had Medigap.
How long do we have to switch back to Medigap?
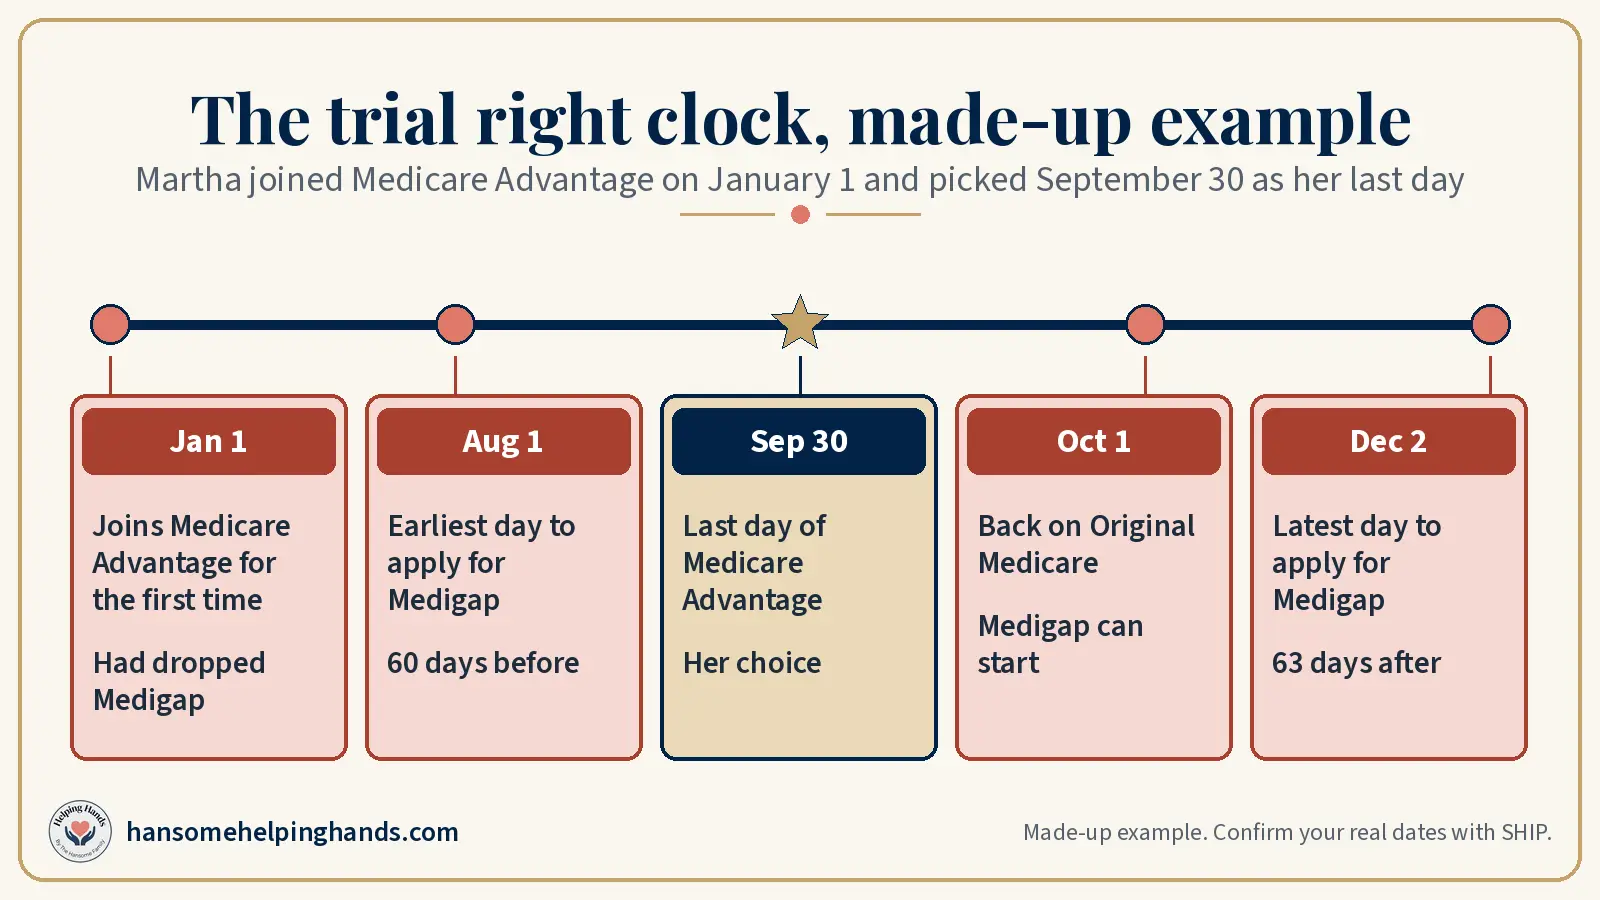
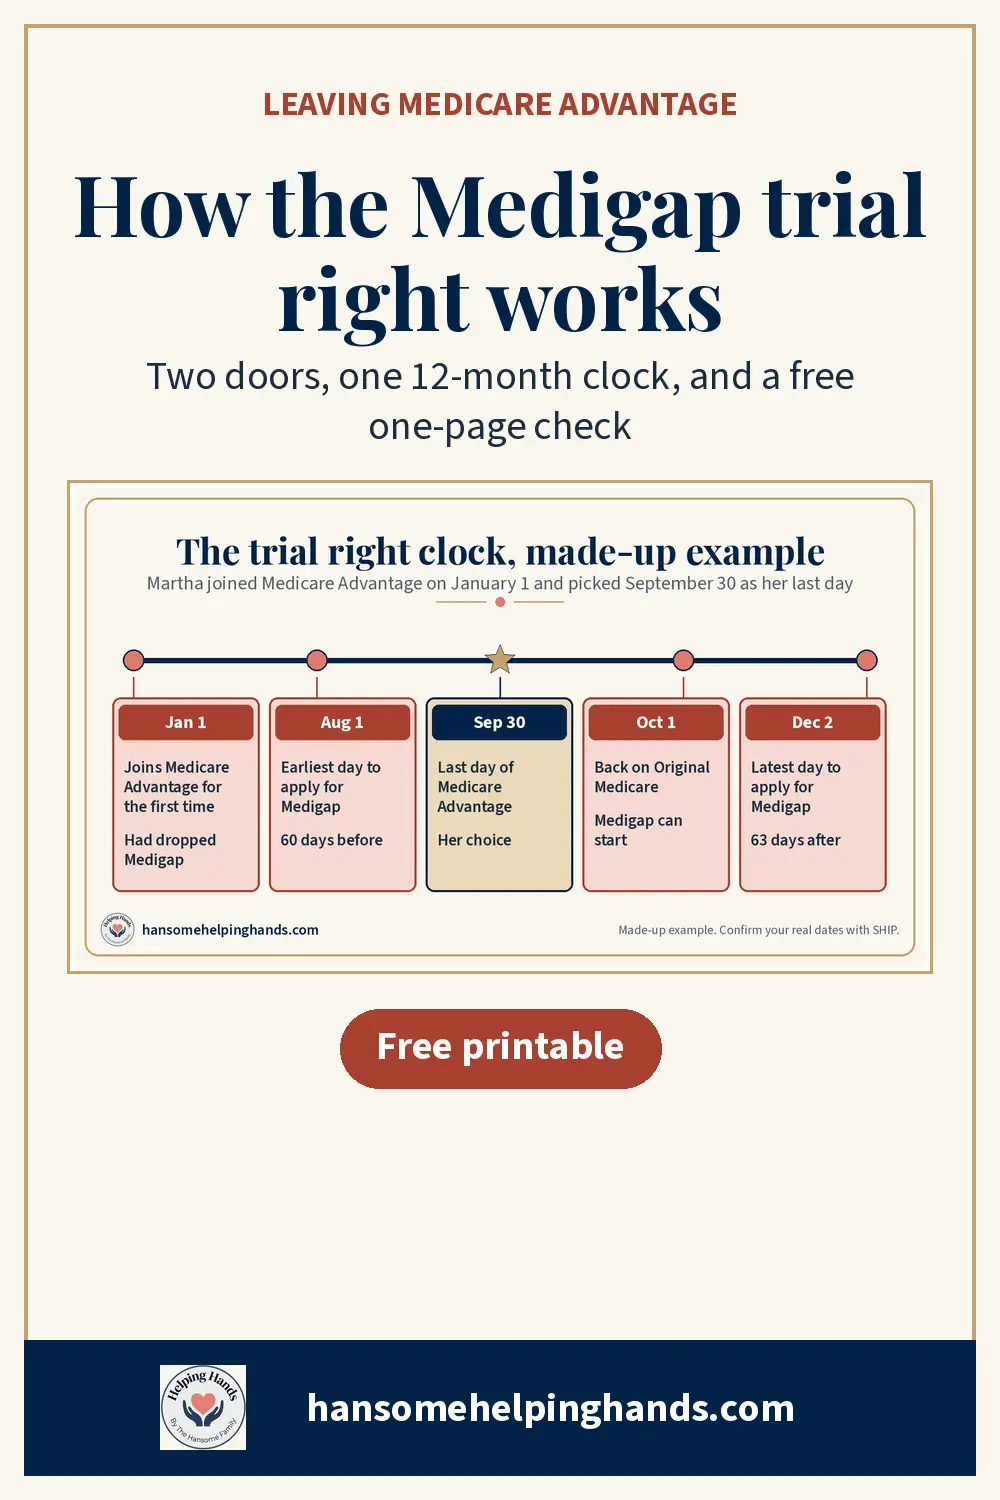
Two clocks run at once. The trial right lasts 12 months from the day she first joined Medicare Advantage. The Medigap application window opens 60 days before her Medicare Advantage coverage ends and closes 63 days after it ends. Medigap cannot start until the Medicare Advantage coverage ends, so plan the dates together.
Picture this as a made-up example: Martha dropped her Medigap policy and joined a Medicare Advantage plan for the first time on January 1. By summer she wants out, and she picks September 30 as her last day in the plan. Counting from that date, the earliest she can apply for Medigap is August 1 (60 days before), and the latest is December 2 (63 days after). She can be back on Original Medicare on October 1, with Medigap starting the same day if it is approved in time.
Two fine-print notes from the Choosing a Medigap Policy guide. First, trial rights may last an extra 12 months in certain circumstances, so ask your State Insurance Department if the plan ended on its own. Second, if the plan is leaving Medicare, stops serving your area, or you move out of its service area, that is a different guaranteed issue right with its own dates. Our guide to what to do when a Medicare Advantage plan is ending walks through that one.
Which trial right door fits Mom?
Check two facts first: whether this is her first time in any Medicare Advantage plan, and how many months she has been in it. Then check whether she dropped a Medigap policy to join, or joined at 65 when first eligible for Part A. Tap each made-up case below to see which door seems to fit.
Case 1: Mom dropped her Medigap Plan G last January to try Medicare Advantage for the first time. It is now October.
Door A, likely. She is inside her first 12 months, so she can ask her old company for that Plan G back if it still sells it. She can apply as early as 60 days before her plan ends.
Case 2: Dad joined Medicare Advantage when he first got Part A at 65, eight months ago. He never had Medigap.
Door B, likely. He joined when first eligible at 65 and is still in the first year, so he can buy any Medigap policy sold by an insurance company in his state.
Case 3: Grandma has been in Medicare Advantage for three years and wants Medigap during Open Enrollment.
No federal trial right. She can still switch to Original Medicare, but outside her Medigap Open Enrollment Period Medicare.gov says there is no federal guarantee an insurer will sell her a policy. Ask SHIP about state rules before she drops the plan.
Case 4: Mom left Medicare Advantage years ago, went back to Original Medicare, and joined a new Medicare Advantage plan this spring.
Probably not a trial right, because both doors are about a first time in Medicare Advantage. She may still have rights under state law, so call SHIP before anyone cancels anything.
What order should we do things in?
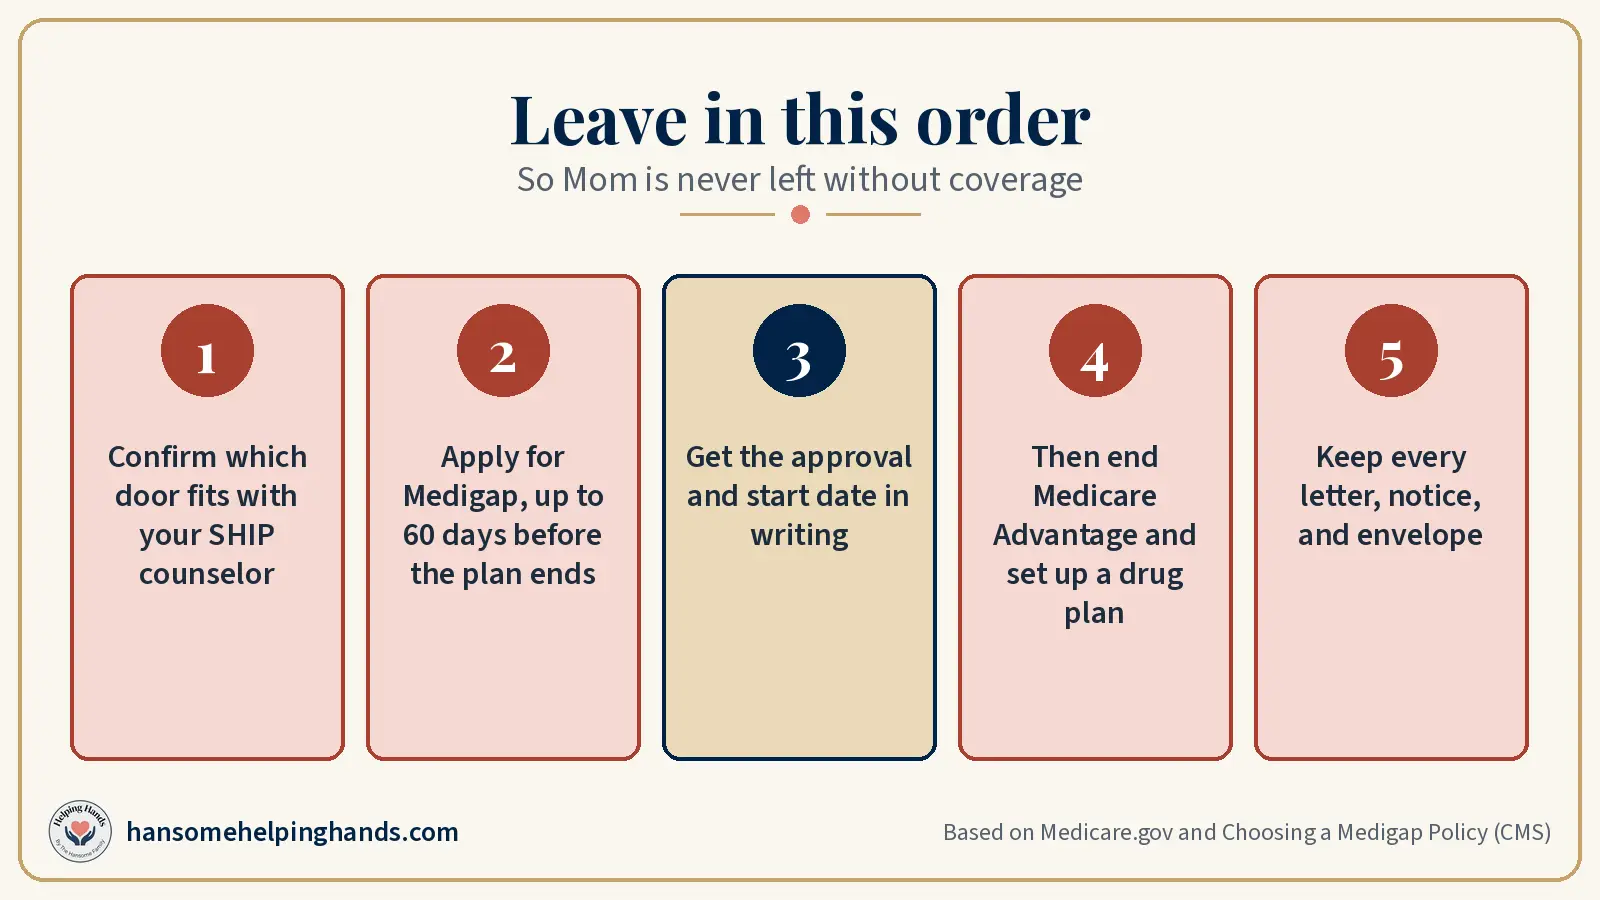
Medigap first, then the exit. Confirm which door fits with SHIP, apply for Medigap inside the window, and get the approval and start date in writing. Only then end the Medicare Advantage plan and line up a separate drug plan, so Mom never has a gap in health or drug coverage.
Step 1: Find the dates
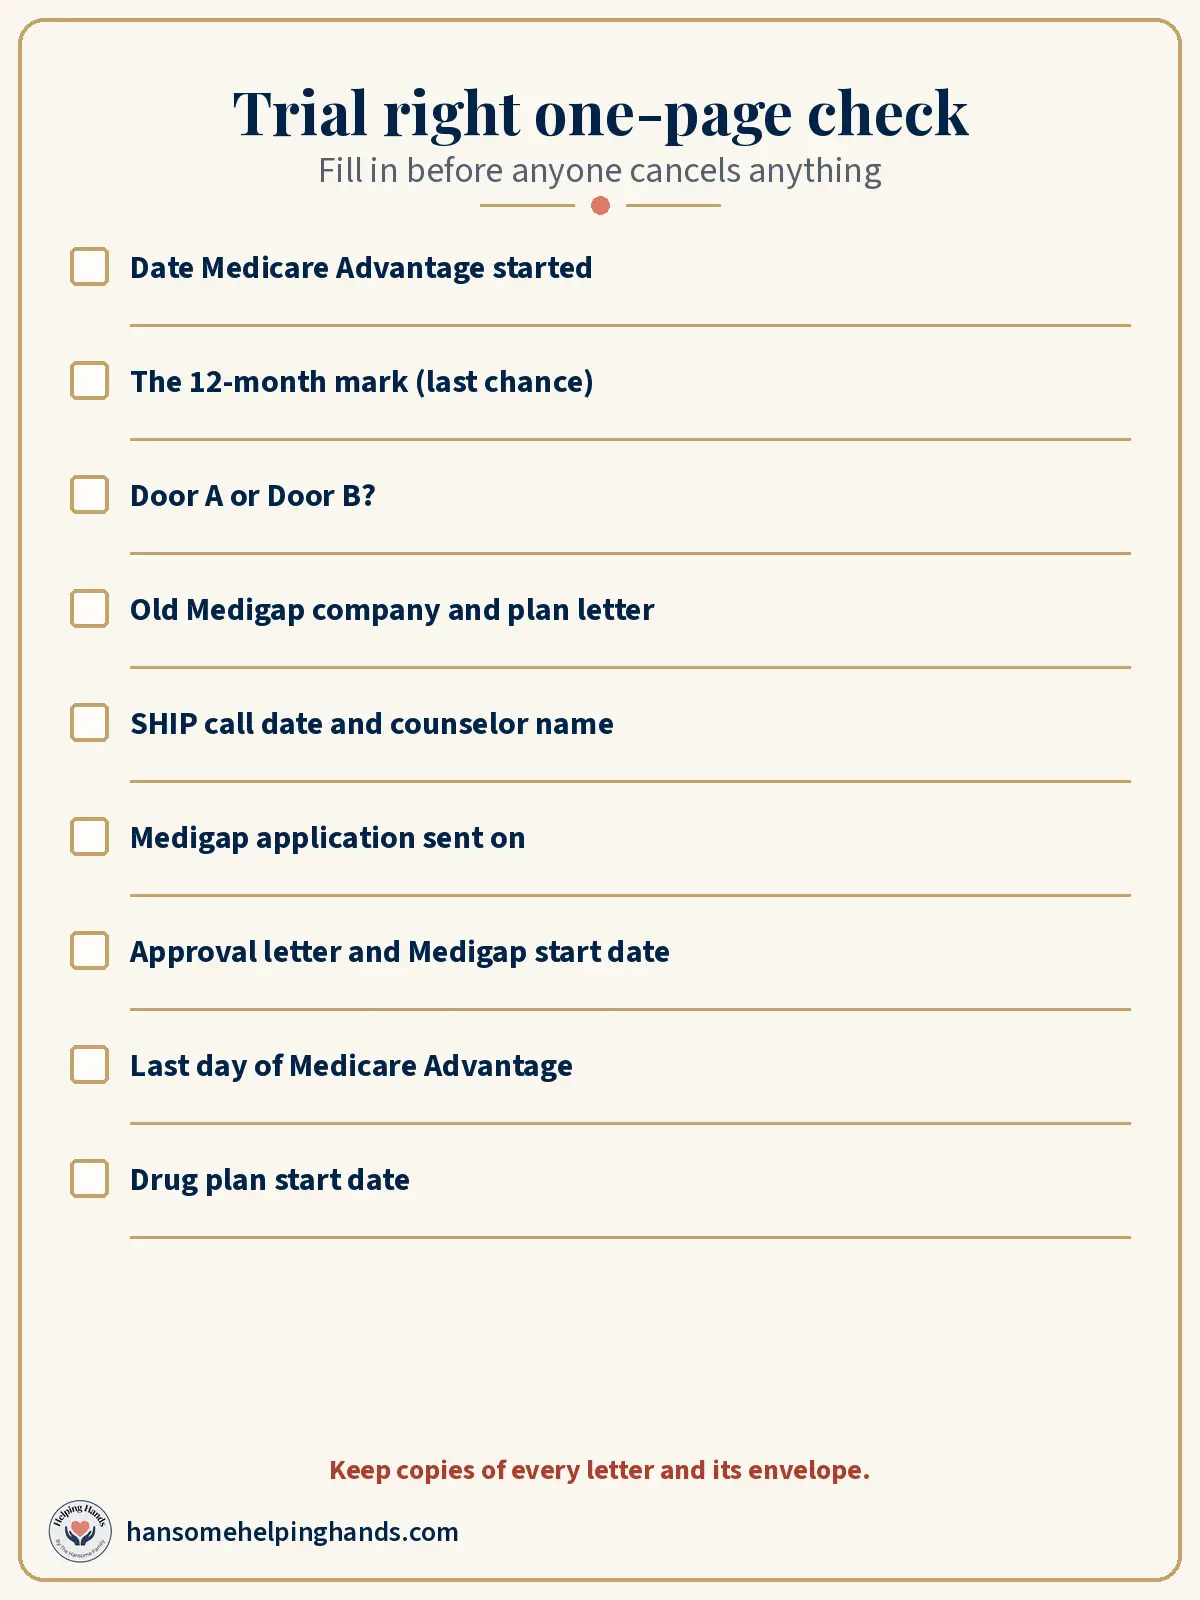
Pull the Medicare Advantage welcome letter or enrollment confirmation that shows the start date, and any old Medigap paperwork (company, plan letter, end date). Every deadline is counted from these dates. When we built our Don't Lose Medigap: MA Trial Right File, we put the plan start date on page one for exactly that reason.
Step 2: Call SHIP before anyone cancels
Your State Health Insurance Assistance Program gives free, unbiased counseling. Find yours at shiphelp.org, or call 1-800-MEDICARE (1-800-633-4227, TTY 1-877-486-2048). Ask which door fits, which plans your state lets you buy, and whether your state adds any rights.
Step 3: Apply for Medigap with proof
Apply to the Medigap insurer inside the window. Federal law says the guarantee applies when you submit evidence of the date of termination or disenrollment along with the application (Social Security Act 1882(s)(3)). The Medigap guide also says to keep letters, notices, emails, and the postmarked envelopes they came in.
Step 4: Then leave the plan and set up drug coverage
Medicare.gov says to contact your Medicare Advantage plan to see if you can disenroll, and that most Medigap policies do not automatically cancel when you join Medicare Advantage. Medigap plans sold after 2005 do not include drug coverage, so line up a separate Medicare drug plan. Going 63 days or more without creditable drug coverage can mean a late enrollment penalty on your Part D premium.
Tap to tick, your progress saves on this device
Myth or fact: what do families get wrong about leaving Medicare Advantage?
The big one is thinking Open Enrollment brings Medigap back. It brings Original Medicare back, but a Medigap insurer can still ask health questions unless a guaranteed issue right applies. The other common slips are dropping the plan before Medigap is approved and forgetting drug coverage. Tap each card to check.
Myth: Open Enrollment guarantees Mom a Medigap policy.
Fact: Open Enrollment lets her change how she gets Medicare. Her Medigap Open Enrollment Period is one time only, and outside it there is no federal guarantee unless a right like the trial right applies.
Myth: joining Medicare Advantage cancels Medigap automatically.
Fact: Medicare.gov says most Medigap policies do not automatically cancel when you join Medicare Advantage. Medigap also cannot pay Medicare Advantage costs, which is why many people drop it.
Myth: the trial right resets every time you switch plans.
Fact: Medicare.gov describes a single 12-month trial right period tied to the first time you join Medicare Advantage. Some circumstances extend it, so ask your State Insurance Department.
Myth: drop the plan first, then shop for Medigap.
Fact: you can apply as early as 60 days before the plan ends. Getting approval first avoids a scramble, and Medigap cannot start until the Medicare Advantage coverage ends anyway.
Myth: Medigap will cover Mom's prescriptions.
Fact: Medigap plans sold after 2005 do not include drug coverage. Join a separate Medicare drug plan, and avoid a gap of 63 days or more without creditable coverage.
Myth: an agent can sell Mom a Medigap policy while she stays in Medicare Advantage.
Fact: Medicare's booklet says it is illegal for anyone to sell you a Medigap policy while you are in Medicare Advantage unless you are switching back to Original Medicare.
Where can we get free help with the dates?
Start with your State Health Insurance Assistance Program at shiphelp.org. SHIP counseling is free, local, and unbiased. You can also call 1-800-MEDICARE, and your State Insurance Department can explain state rights or help if an insurer refuses a guaranteed issue application. Bring the plan start date and every letter to the call.
Rules can vary by state, and some states give more chances to buy Medigap than federal law does. The Choosing a Medigap Policy guide says to call SHIP to make sure you qualify, and your State Insurance Department if you are denied in a guaranteed issue situation.
Still deciding whether to stay in a plan for next year? Our Annual Notice of Change decoder shows what to circle on the fall letter, and the Medicare Open Enrollment checklist walks through the October 15 to December 7 window. If a hospital stay is what made you rethink the plan, keep our hospital discharge checklist handy. For the bigger picture, start at our Medicare and Medicaid help hub.
Want the paperwork already laid out? Our Don't Lose Medigap: MA Trial Right File is a 14-page printable for this exact situation: a Door A or Door B worksheet, the 12-month clock, the 60 and 63 day apply window page, a proof checklist, and SHIP and 1-800-MEDICARE call logs. It does not quote or recommend plans. Get it on Gumroad for $12.99 (price checked October 20, 2026) or see it on Etsy.
Frequently asked questions
Can you switch from Medicare Advantage back to Original Medicare?
Yes. Anyone can drop a Medicare Advantage plan and return to Original Medicare during Open Enrollment, October 15 to December 7, or during the Medicare Advantage Open Enrollment Period, January 1 to March 31. Medigap is the harder part. Without a trial right or another guaranteed issue right, an insurer may turn you down or charge more.
What is the Medigap trial right?
It is a federal protection for people trying Medicare Advantage for the first time. If they return to Original Medicare within the first 12 months, insurers must sell certain Medigap policies without health questions. Which policies depends on whether they dropped Medigap to join, or joined Medicare Advantage when first eligible at 65.
How long do I have to apply for Medigap after leaving Medicare Advantage?
For a trial right, Medicare says you can apply as early as 60 days before your Medicare Advantage coverage ends and no later than 63 days after it ends. Medigap cannot start until the Medicare Advantage plan ends, so ask the insurer to put the approved start date in writing.
Do I need a separate drug plan if I go back to Original Medicare?
Usually, if you want drug coverage. Medigap plans sold after 2005 do not include prescription drug coverage, and Medicare says the trial right also lets you join a separate drug plan. Going 63 days or more without creditable drug coverage can add a late enrollment penalty to your Part D premium.
Does every state follow the same Medigap rules?
Federal law sets the floor, and some states give extra rights to buy a Medigap policy. Massachusetts, Minnesota, and Wisconsin also set up their Medigap plans differently. Before anyone cancels a plan, call your State Health Insurance Assistance Program (SHIP) or State Insurance Department and ask what your state allows.
Please note: This guide explains official rules in plain English. It is not legal or insurance advice and we are not affiliated with Medicare or any government agency. Confirm details with Medicare (1-800-MEDICARE), your plan, your State Health Insurance Assistance Program (SHIP), or an elder law attorney.
Sources
- Medicare.gov: When can I buy a Medigap policy? (Medicare Advantage answers). Checked 2026-10-20
- Medicare.gov: Learn how Medigap works (Medigap and Medicare Advantage). Checked 2026-10-20
- CMS and NAIC: Choosing a Medigap Policy (guaranteed issue and trial rights, pages 16 to 18). Checked 2026-10-20 (CMS Product No. 02110, March 2026)
- Medicare.gov: Understanding Medicare Advantage Plans (trial right to buy Medigap). Checked 2026-10-20 (CMS Product No. 12026, April 2026)
- Medicare.gov: Special Enrollment Periods (trial period situations). Checked 2026-10-20
- Medicare.gov: Medigap Open Enrollment and guaranteed issue rights. Checked 2026-10-20
- Social Security Act section 1882(s)(3), guaranteed issue (SSA compilation). Checked 2026-10-20
- Medicare.gov: Creditable prescription drug coverage (the 63 day rule). Checked 2026-10-20
- SHIP: State Health Insurance Assistance Programs. Checked 2026-10-20
Save this guide for later
Keep reading
- Your Medicare Plan's Annual Notice of Change: What to Check Before December 7
- Mom's Medicare Advantage Plan Is Ending or Her Doctor Left: What Now?
- Medicare Open Enrollment: A Kitchen-Table Checklist for Helping a Parent
- Hospital Discharge Checklist: What to Ask Before Mom or Dad Leaves
- Medicare and Medicaid Help for Families: start here
- Does Medicare Pay for Home Help? Home Health vs Home Care, Sorted
- Got a NOMNC? How a Medicare Fast Appeal Works
- The Medicare Prescription Payment Plan: Spreading Drug Costs Across the Year
- The Pharmacy Said No: How to Ask for a Part D Coverage Determination
- Medicare Savings Programs: Help Paying the Part B Premium
- Extra Help for Medicare Drug Costs: Who Qualifies and How to Apply
- Medicaid Look-Back Period in Plain English: Myths vs Facts
- Who to Notify When Someone Dies: A Printable US Checklist
- How to Prepare for an IEP Meeting: A Parent's Countdown Checklist
- Dementia Behavior Log: How to Spot the Patterns the Doctor Needs to See
- Questions to Ask When Touring Assisted Living (and What to Watch For)
- All guides